Business
Pest Control for Businesses: The Hidden Costs of Waiting Too Long

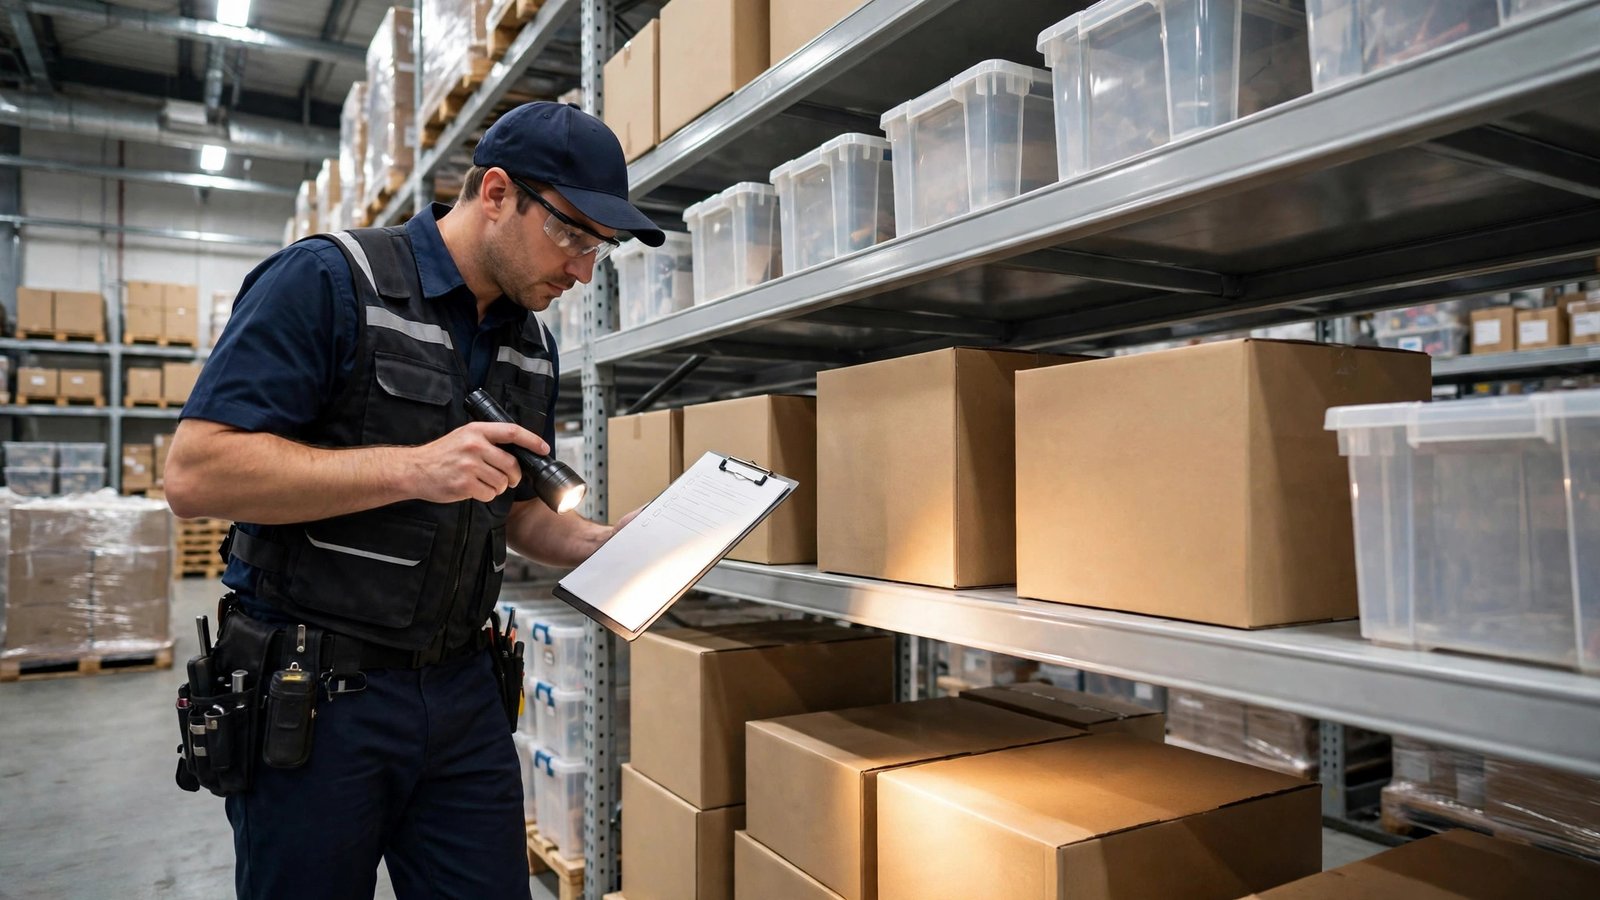
For a business, pest control can seem like a background task until a complaint, failed inspection, or damaged shipment makes it urgent. Pest activity can develop quietly in retail stores, restaurants, offices, warehouses, and other commercial properties. A practical prevention plan helps protect customers, employees, inventory, and the reputation you have worked to build.
Pest Problems Often Begin Before Anyone Notices
Most commercial pest problems do not start with a dramatic infestation. They develop around everyday conditions: crumbs beneath shelving, moisture near a mop sink, gaps around loading doors, or cardboard left in storage for too long.
By the time an employee reports mouse droppings or a customer spots a cockroach, pests may already have established a route through the building. They look for reliable sources of food, water, and shelter, often using wall voids, utility openings, drains, and cluttered storage areas.
A clean reception area does not necessarily mean the entire facility is protected. Back rooms, kitchens, waste areas, delivery zones, and mechanical spaces can create opportunities that are easy to overlook during ordinary cleaning.
Businesses that avoid major infestations treat pest prevention as part of routine operations. They look for the conditions that attract pests instead of waiting until visible activity forces an urgent response.
Routine Inspections Make Prevention Practical
A business does not need to wait for a serious infestation before arranging a professional assessment. Regular inspections can identify early activity and conditions that make a property vulnerable.
A useful program may include monitoring devices, inspection of entry points, checks for moisture and food sources, sanitation reviews, activity logs, and recommendations for structural repairs. Findings should be documented so managers can see whether the same areas keep attracting pests.
Seasonal changes also deserve attention. Warmer weather can increase activity from ants and stinging insects, while cooler conditions may encourage rodents to seek shelter indoors. Nearby construction, landscaping changes, and shifts in waste storage can also alter pest pressure.
If you are evaluating a local pest control company, look for a provider that can explain inspection findings, recommend practical prevention measures, and document follow-up. A service visit should produce useful information, not just a treatment receipt.
Your Industry Changes the Risk
Different businesses create different pest pressures. Restaurants must manage food residue, grease, drains, and waste. Warehouses may face rodents and stored-product pests around inventory and loading docks. Offices can experience ants, spiders, and occasional rodent activity, particularly near kitchens and break rooms.
Salons, childcare facilities, medical offices, and retail stores have their own concerns. A customer-facing business must protect its image, while facilities serving children, patients, or food may have additional sanitation and safety obligations.
A generic treatment schedule can miss these differences. A food-service location may need close monitoring of food preparation and waste areas. A warehouse may require attention to receiving procedures, stock rotation, and gaps around dock doors. The plan should reflect how the building is used, where goods move, and which areas are most vulnerable.
Matching pest management to the property’s actual risks makes inspections more useful and helps direct resources where they can have the greatest effect.
A Pest Sighting Can Undermine Customer Trust
Customers may forgive a delayed order or a minor service issue. Seeing a cockroach near a counter or a rodent in a storage area can create a much stronger reaction because people associate pests with poor hygiene and inadequate management.
That impression can appear in online reviews, social media posts, and conversations with potential customers. In hospitality and food service, even one visible incident can influence whether someone feels comfortable returning.
Employees are affected too. Repeated pest sightings in break rooms, stockrooms, or shared workspaces can make staff question whether management takes workplace conditions seriously. That can damage confidence and create additional complaints for supervisors to handle.
Pest management is therefore not simply a facilities expense. It supports the experience customers and employees associate with your business. Protecting that experience requires consistent attention, not a response that begins only after someone raises a concern.
Integrated Pest Management Connects the Whole Building
Pest control works best when it is coordinated with facility maintenance. A damaged door sweep, cracked foundation opening, leaking pipe, or poorly managed dumpster area can keep attracting pests even after treatment.
Integrated pest management, commonly called IPM, combines monitoring, sanitation, exclusion, habitat reduction, and targeted control when needed. It focuses on identifying why pests are present and correcting the conditions that allow them to survive.
The CDC’s overview of integrated pest management explains this prevention-focused approach, including inspection, identification, and addressing the conditions that support pest activity. The principle applies beyond a single treatment: businesses need ongoing attention to the environment that surrounds the problem.
This requires communication between pest professionals, maintenance teams, cleaning staff, and managers. When everyone understands what has been found and who is responsible for corrective action, recurring access points are less likely to be ignored.
Staff Habits Can Strengthen or Undermine the Plan
Even a well-designed service plan can struggle if daily routines provide pests with food, water, and shelter. Unsealed snacks, uncovered waste bins, wet cleaning equipment, and delivery cartons left on floors can all contribute to the problem.
Training does not have to be complicated. Staff should know how to store food, secure rubbish, report leaks, keep storage areas orderly, and identify signs such as droppings, gnaw marks, insect activity, or damaged packaging.
A short opening or closing checklist can help make these tasks consistent. Employees should also know whom to contact when they notice activity, rather than attempting treatments themselves or assuming someone else has reported it.
The EPA’s reference guide to integrated pest management describes how sanitation, maintenance, monitoring, staff education, and reducing access to food, moisture, and shelter contribute to prevention. Although the guide focuses on schools, these building-management principles are useful in other workplaces too.
Choose a Provider Who Communicates Clearly
Applying a treatment is only one part of professional pest management. Businesses also need to understand what was found, what actions were taken, and what should happen next.
A useful service report identifies the areas inspected, evidence of activity, contributing conditions, recommendations, and any follow-up required. Clear communication helps managers prioritize repairs, track recurring problems, and explain decisions to property owners or department heads.
Ask how the provider adapts its approach to your industry, schedules work around business operations, and communicates urgent findings. Also confirm that any pesticide use complies with applicable product labels and local requirements.
The right provider should act as a knowledgeable partner, helping your team understand risks rather than leaving you with vague notes or repeated treatments that do not address the underlying cause.
Make Pest Prevention Part of Business Operations
Pest problems can emerge even in businesses that appear clean and well managed. Seasonal changes, deliveries, nearby construction, or a small maintenance lapse can create an opportunity for pests to enter and settle.
The answer is not to operate in constant fear of an infestation. It is to build a reliable system: inspect vulnerable areas, correct building defects, maintain good sanitation, train employees, document activity, and work with a qualified provider when needed.
These measures help limit disruption, protect customer confidence, and reduce the likelihood that a minor issue becomes an expensive business problem. When pest control is treated as part of everyday facility management, it becomes more predictable and easier to oversee.
For businesses that depend on clean, welcoming, and dependable premises, prevention is not an optional extra. It is part of protecting the operation every day.

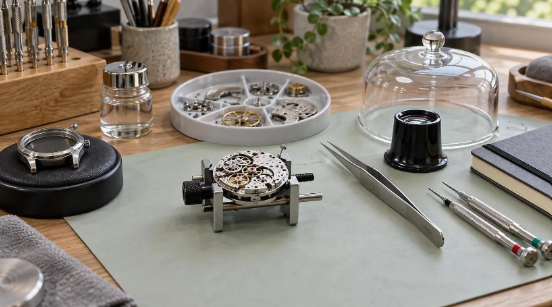
Watch Repair Tools Australia is building a local resource for the people who keep watches working, combining specialist stock with practical guidance for the repair bench. From the outside, watch repair looks like a craft built on patience and a steady hand. At the bench, it also depends on knowing what fits, what a job calls for and where to find it. For Australian watchmakers, collectors and students, that can mean working through several catalogues before a repair can even begin.
Ben Holdaway, a lifelong watch enthusiast, built Watch Repair Tools Australia around that practical problem. The independent Australian business stocks specialist tools, parts and workshop consumables locally. Its range is organised around jobs repairers recognise, from inspecting a movement and opening a case to fitting hands and checking how a watch runs.
Making specialist knowledge easier to find
In a trade where a fraction of a millimetre can determine whether a tool or part fits, clear specifications matter. The company’s published guides help readers distinguish between similar fittings, understand what a tool can do and recognise when a job needs an experienced watchmaker. That information gives a collector starting out and a repairer checking a specification a common place to begin. Recent guides cover how to release a stuck spring bar without damaging the case and how to measure replacement hands before fitting them.
Customer requests also help shape the range. That gives the business a way to hear what Australian repairers struggle to source and which items they need repeatedly. Local stock and dispatch matter most when an otherwise straightforward job is waiting on one missing part or bench tool.
Supporting the people behind the repair
Watch Repair Tools Australia occupies a specific place in the local trade. It supplies the bench and publishes reference material for the people working at it. By making specialist equipment and repair knowledge easier to find locally, the business is building a reference point for Australian watch repair.

The process of borrowing from a lender includes far more than the selection of a lender and the determination of the sum you want to borrow. The lender analyzes your financial documentation in order to know how well your business operates and whether it is able to pay back the loan. If you are asking yourself how can I get a business loan, preparing the necessary paperwork before submitting an application will be helpful.
What Financial Documents Do You Need Before Applying for a Business Loan?
Financial documents are usually sought out by lenders in order to determine how your business makes money and allocates finances. The specific documents that need to be provided depend on the lender, the loan amount, and the method of financing used. Here are six important documents to prepare when considering how can I get a business loan.
1. Business and Personal Tax Returns
Tax returns assist lenders in validating the income stated in your application, and they give information about your firm’s historical financial performance. If you are running a sole proprietorship or a small business, your lender will also consider your personal tax documents. Such documents will enable them to determine your source of income and your financial standing. Maintaining updated tax documents will simplify your application process when exploring how can I get a business loan.
2. Bank Statements of Your Business
Bank statements of your business contain all details about deposits and withdrawals that have been made to your business bank account. The lender may ask for bank statements from three to six months ago that would help them see your deposits, withdrawals, balance in your account, and other details. This information will help them see your regular income and expenses. Your regular deposits and good balance in your account will work positively for you. If you are thinking about how can I get a business loan, ensure that your bank statements show your business activity properly.
3. Profit and Loss Statements
Profit and loss statements illustrate how much income is generated by your business and what amount of expenses are incurred within a given period of time. These statements usually include sales, operating costs, gross profit, and net profit or loss. The lenders rely on these statements to determine whether your business is profitable or not and how good it is at controlling its expenses. They can compare the financial figures during various periods to track changes in your revenues and operating costs. This way, including the profit and loss statement in your application will be useful when you are exploring how can I get a business loan.
4. Balance Sheet
Balance sheets offer information about your company’s financial situation as of a particular date. They involve three key items that include assets (items owned by your business), liabilities (money owed), and equity of the owner (the owner’s financial stake after deducting liabilities from the total assets). The bank evaluates these aspects to see what resources you have and the current level of your obligations. It will help them determine your financial status and readiness to take new loans.
5. Cash Flow Statements & Projections
Cash flow statements depict where the money flows in and out of your business within a specified period. These statements describe the flow of cash from operating, investing, and financing activities. The lender analyzes these statements to ascertain if your business is capable of creating enough cash flows to cater to the daily needs of your business and pay off loans. Future cash flow projections could also be asked by your lender to analyze your future financial status.
How Proper Documentation Can Streamline the Loan Process
Having all financial records in order will simplify the application process for both the borrower and the lending agency. This will prevent unnecessary delays, give an accurate picture of the borrower’s financial standing, and help the lending institution evaluate the borrower’s ability to repay the loan.
- Reduces application delays: By maintaining an organized record of tax forms, bank statements, and other financial documentation, lenders can obtain the required data without having to ask for it again.
- Helps in demonstrating repayment ability: The latest financial statements, including profit and loss accounts and balance sheets, enable the lender to have better insight into your revenues, expenditures, and financial obligations.
- Easier to determine eligibility: You may be asking yourself, ‘how do I qualify for small business loan financing?’ Providing comprehensive documentation will make it easy for the lender to check your creditworthiness, business performance, and repayment capability.
- Provides alternative means of raising capital: In case you are exploring how to get approved for a loan without collateral, then keeping your finances in order will prove the fact that your business is profitable. But, of course, it depends on the lending company’s terms.
Final Words
Having the right financial documents is crucial when applying for financing for a business venture. Tax papers, bank statements, profit/loss statements, balance sheets, cash flow statements, and business plans are some of the financial documents that lenders need in order to gauge your financial standing and capability to repay the loan. When preparing to apply for the loan, ensure that your paperwork is in order by checking your numbers and verifying what the lender wants from you in terms of financial paperwork. When you are exploring how can I get a business loan, having the right financial data might help you a lot.

Choosing a new vehicle in Sarasota, Florida, should begin with the way you actually live. A vehicle that handles weekday commutes on U.S. 41, weekend beach trips, school pickup, airport runs, or work equipment will feel more useful long after the excitement of buying it fades.
For example, someone searching for a truck for sale near me may need more than a powerful engine. Bed length, payload, trailer needs, garage clearance, passenger space, and ease of parking can matter just as much when the truck becomes part of a daily Sarasota routine.
Local driving can include short errands, busy shopping areas, coastal outings, longer trips toward Tampa or Fort Myers, and sudden wet-weather conditions. Think about where the vehicle will spend most of its time, including your driveway, garage, workplace, and regular parking spaces.
Before comparing trim levels, write down the needs that occur every week rather than the needs that might occur once a year. This simple step makes it easier to separate must-have features from appealing extras.
When comparing options at Sarasota car dealerships, bring that list with you. A clear list helps you ask better questions and compare vehicles by usefulness instead of relying on a quick first impression.
1. Start With Real Life, Not Vehicle Badges
The best vehicle for one household may be inconvenient for another. A solo commuter may value easy parking and efficiency, while a family may need rear-seat access, room for a stroller, and luggage space. A contractor or frequent boater may place hauling and towing ability at the top of the list.
- How many miles do you normally drive on weekdays?
- Do you drive mainly on city streets, highways, or a mix of both?
- How many passengers ride with you regularly?
- What items do you routinely carry, such as groceries, golf gear, work tools, or pet supplies?
- Will you need to tow a trailer, boat, or other equipment?
- How often do you take longer road trips?
2. Match the Body Style to the Job
Sedans
Sedans can be a practical choice for drivers who want manageable exterior dimensions, straightforward parking, and comfortable highway travel. Their enclosed trunks may be less convenient for bulky cargo, so bring measurements for items you carry often.
Compact SUVs and Crossovers
Compact SUVs often balance upright seating, flexible cargo space, and everyday maneuverability. They can suit small families, pet owners, and drivers who want easier loading than a traditional sedan may provide.
Midsize and Three-Row SUVs
A larger SUV may make sense for regular carpools, visiting family, or road trips with several passengers. Check third-row access, usable cargo room with every seat occupied, and whether the vehicle still fits comfortably where you park.
Pickup Trucks and Cargo Vans
Trucks and vans are useful when tools, materials, equipment, or trailers are central to your routine. Compare the specific vehicle’s payload and towing ratings, bed or cargo-area layout, tie-down points, and available storage before assuming a larger model is automatically the better fit.
3. Compare Gas, Hybrid, Plug-In Hybrid, and Electric Power
Each powertrain can serve a different type of driver. Gasoline vehicles offer familiar refueling for drivers who take frequent longer trips. Hybrids can appeal to drivers seeking improved efficiency without relying on plug-in charging. Plug-in hybrids combine battery driving with gasoline backup, while electric vehicles can be especially convenient for people who have dependable charging where they live or work.
Electric-vehicle shoppers should confirm overnight charging access, estimate normal daily mileage, identify charging stops on regular travel routes, and ask whether a home electrical upgrade may be appropriate. Heat, air conditioning use, driving speed, and cargo can affect an EV’s energy use, so plan with a margin rather than choosing based only on a best-case estimate.
4. Plan for Full Ownership Costs
A payment is only one part of the vehicle budget. Include insurance, fuel or charging, scheduled maintenance, tires, registration, taxes, and accessories such as a trailer hitch, roof carrier, floor protection, or charging equipment.
A useful planning formula is: total monthly vehicle cost = payment + insurance + fuel or charging + maintenance + registration. The U.S. Department of Energy’s vehicle cost calculator lets shoppers compare estimated ownership costs using their driving habits and fuel assumptions.
5. Make Safety a Priority Before Convenience Features
Large touchscreens and premium finishes may be enjoyable, but safety deserves a separate review. Check outward visibility from the driver’s seat, rear-seat access, head restraint positioning, camera clarity, and the controls you may need while driving.
Look for the driver-assistance and safety equipment included on the exact trim, not simply advertised as available for the model. Useful items to evaluate include automatic emergency braking, blind-spot monitoring, rear cross-traffic alert, lane-support features, parking sensors, and adaptive cruise control. Review vehicle safety ratings and recall information before narrowing your final choices.
6. Use the Test Drive Well
A brief loop around the block is rarely enough. Set the seat, steering wheel, and mirrors as you would for a normal drive, then test how naturally the vehicle fits you.
- Check front, side, and rear visibility.
- Try entry and exit from every seat your household will use.
- Bring a child seat, stroller, pet carrier, golf bag, or work item when relevant.
- Test acceleration, braking, turning, parking, and highway merging if possible.
- Notice road noise, seat support, climate-control performance, and control placement.
7. Create a Vehicle Scorecard
Rate each finalist from one to five in the categories that matter most to you. This keeps one exciting feature from hiding a major practical drawback.
- Budget: Does the full monthly cost fit comfortably?
- Space: Do regular passengers and cargo fit without compromise?
- Comfort: Will the seats and ride remain pleasant on longer drives?
- Safety: Does the vehicle provide the visibility and protection you want?
- Efficiency: Do fuel or charging needs match your routine?
- Flexibility: Can it handle occasional visitors, gear, or weekend plans?
8. Complete a Final Buying Checklist
- Confirm the total price after taxes and fees.
- Verify the equipment included on the exact vehicle.
- Review warranty coverage and maintenance requirements.
- Check for open recalls.
- Get an insurance estimate before finalizing the purchase.
- Measure garage, driveway, and usual parking spaces.
- Ask whether the vehicle will still suit your household in three to five years.
The right new vehicle is not necessarily the biggest, quickest, or most feature-packed option. For Sarasota drivers, the strongest choice is the one that fits daily travel, passengers, cargo, parking, comfort, safety, and long-term costs with the fewest compromises.

Asparagus Risotto in an Instant Pot: What You Gain, What You Trade, and How to Get It Right

How Watch Repair Tools Australia is building a local resource for the repair trade

How Can I Get Business Finance? The Financial Documents Required Before Application
Who Is Gale Burnick? The Story Of George R. R. Martin’s Ex Wife

Who Is Hermann Nicoli? The Full Story Of Candice Swanepoel’s Former Fiancé

Who Is Alicia Dove? The Life Story Of Corey Taylor’s Wife
-
Celebrity4 months ago
Who Is Gale Burnick? The Story Of George R. R. Martin’s Ex Wife
-
 Celebrity4 months ago
Who Is Hermann Nicoli? The Full Story Of Candice Swanepoel’s Former Fiancé
-
 Celebrity4 months ago
Who Is Alicia Dove? The Life Story Of Corey Taylor’s Wife
-
 Celebrity4 months ago
Meet Carole Rogers: Everything to Know About Kenny Rogers’ Daughter
-
 Celebrity4 months ago
Who Is Sydney Davis? The Full Story Of Billy Bush’s Ex Wife
-
 Celebrity4 months ago
Who Is Anna Hillinger? The Full Life Story Of Mike Shinoda’s Wife
-
 Celebrity4 months ago
Who Is Demacio Castellon? Life Story Of Nelly Furtado’s Ex Husband
-
 Blog3 months ago
What Is Sosoactive? A Complete Guide to the Digital Platform